Service Used Abroad Test in Turkey: What Remote Workers Must Prove
For Turkish service export tax benefits, a foreign client is not enough. The service must be used or benefited from abroad. If the work supports Turkish operations, Turkish custome
Last reviewed: 18 August 2026
Short Answer
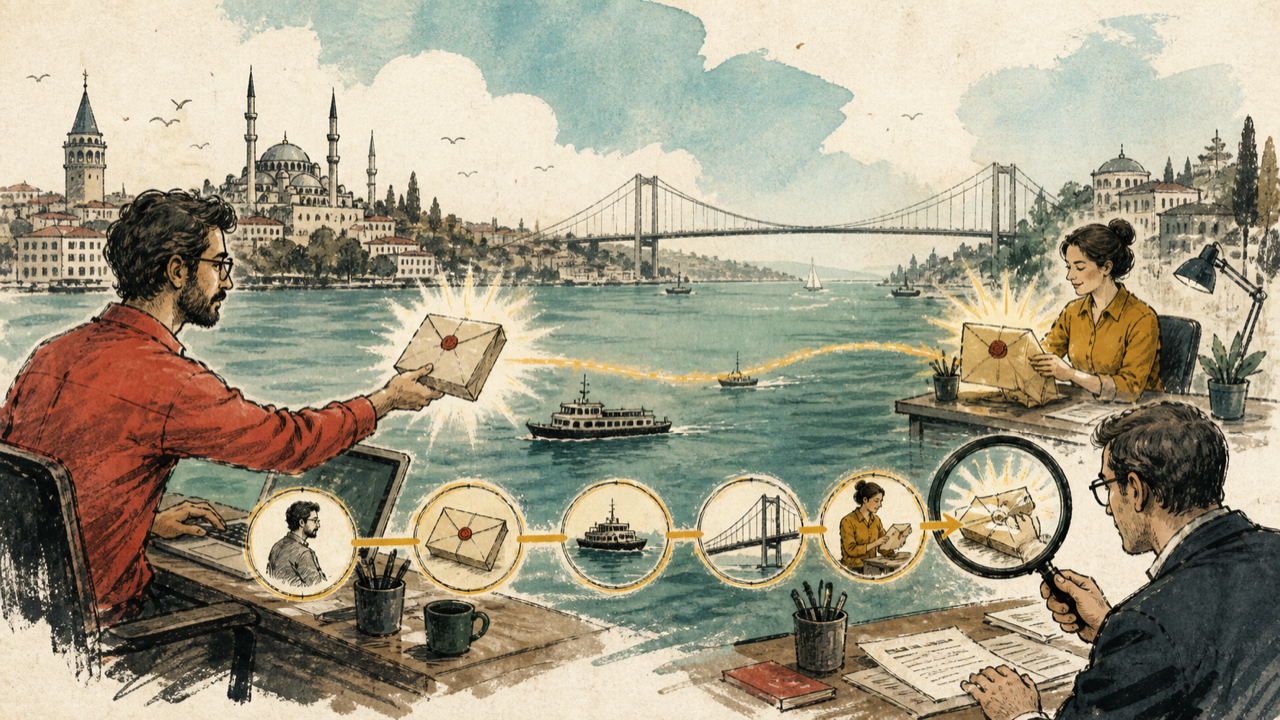
For Turkish service export tax benefits, a foreign client is not enough. The service must be used or benefited from abroad. If the work supports Turkish operations, Turkish customers, a Turkish subsidiary or a Turkish market, the service-used-abroad condition may fail and both income tax deduction and VAT exemption can be at risk.
Clean vs Risky Cases
| Case | Risk level |
|---|---|
| Backend software for foreign SaaS used outside Turkey | Lower |
| Design for a foreign brand's Turkish campaign | Higher |
| Data analysis for a UK research project | Lower |
| Consulting for a foreign company's Turkish subsidiary | Higher |
| Engineering drawings for an overseas construction project | Lower |
Evidence to Keep
- Contract scope
- Invoice wording
- Project documentation
- Client confirmation of use abroad
- Delivery records
- Emails showing business purpose
- Separate accounting for Turkish and foreign work
Case Review
Send contract, invoice draft, service description and explanation of where the client uses the output.
Email: info@ozmconsultancy.com
Subject line: Service used abroad test Turkey review
Related Guides
- 100% service export deduction: https://evrenozmen.com.tr/turkey-100-percent-service-export-tax-deduction
- VAT guide: https://evrenozmen.com.tr/hizmet-ihracati-kdv-istisnasi
Durumunuzu Birlikte Değerlendirelim
Yabancı şirketle çalışma modeliniz, müşteri ülkesi, hizmet türü ve mevcut şirket yapınıza göre ilk riskleri görmek için iletişim sayfasından e-posta gönderin.
Doğrudan iletişim: info@ozmconsultancy.com | +90 216 352 29 61 | WhatsApp’tan yazın
Sources
- 100% service export deduction: https://evrenozmen.com.tr/turkey-100-percent-service-export-tax-deduction
- VAT service export guide: https://evrenozmen.com.tr/hizmet-ihracati-kdv-istisnasi
- Turkish Revenue Administration, Presidential Decision No. 11257: https://www.gib.gov.tr/duyuru-arsivi/guncel/17846_11257_sayili_cumhurbaskani_karari_resmi_gazetede_yayimlandi
About the author
- Evren Özmen is an Istanbul-based CPA / SMMM specializing in tax and accounting for remote workers, freelancers and professionals earning income from foreign clients. His practice has supported more than 1,000 remote-working taxpayers. Core topics include employee versus contractor classification, foreign-client invoicing, VAT exemption for exported services, service export deductions, sole proprietorship and limited company compliance. General information only; case-specific review is required before applying any tax position.
Comments
Join the discussionNo comments yet. Be the first to comment.